
Most homeowners don’t find out what their Mulberry home insurance really covers until they file a claim. By then, an outdated dwelling limit, a hurricane deductible bigger than expected, or a missing sinkhole or flood policy can turn a bad day into a long, expensive recovery. The good news is that each of these gaps is easy to check, and easy to fix, before the next storm.
Quick Takeaways
- Local Reality: Hurricanes Ian (2022) and Milton (2024) both brought damaging winds and flooding to Polk County, and the county has documented sinkhole activity, including around Mulberry.
- The Coverage Gap: A policy that only satisfies your lender can leave you short on rebuild cost, stuck with a large hurricane deductible, and unprotected from sinkholes and flood.
- Coverage Options: Right-sized dwelling coverage, wind mitigation credits, and many optional enhancements.
- The Independent Advantage: We’re independent and locally licensed, so we compare multiple carriers and explain your options clearly.
Protecting Your Mulberry Home Takes More Than a Basic Policy
Mulberry has been home to Polk County families since it was incorporated in 1901, and about 78% of Mulberry homes are owner-occupied, a high rate for a small Florida city. For most families here, the home is their largest asset, and that’s exactly what the right policy protects. Learn more about the community in our guide to Mulberry, FL.
Homes around Mulberry vary widely, from older houses near downtown and Mulberry Heights to newer planned communities like Imperialakes and The Preserves at Sundance, plus ranch homes and manufactured homes in areas such as Willow Oak and Bradley Junction. Each type is insured differently. A 1990s ranch, a newer two-story home in a gated community, and a manufactured home can face very different roof requirements, carrier options, and rebuild costs.
A basic policy may be enough to close on a home, but it may not be enough to rebuild it after a major loss. Your coverage should match your home’s construction, roof, replacement cost, and protection features, not just your lender’s minimum requirement.
Storms, Wind, and Hurricane Deductibles
Being inland doesn’t keep Mulberry out of a hurricane’s path. Hurricane Ian in 2022 and Hurricane Milton in 2024 both crossed Central Florida, bringing damaging winds, flooding, and widespread power outages to Polk County. Add a summer storm season that runs June through September, and your roof, your wind coverage, and your deductible all deserve a close look.
Florida homeowners policies carry a separate hurricane deductible. A 2% deductible, based on your dwelling limit, is the most common, and insurers must also offer $500, 5%, and 10% options. For example, a home insured for $300,000 with a 2% hurricane deductible would have a $6,000 deductible for a covered hurricane loss. At 5%, that same home would carry a $15,000 deductible.
The hurricane deductible applies once per calendar year, not per storm, for covered hurricane losses with the same insurer or insurer group. We’ll translate the percentage into a dollar amount for your home, so you can choose a deductible that fits your budget and your savings.
Roofs, Wind Mitigation, and Rebuild Costs
Roof age, roof covering, opening protection, and prior claims are major Florida underwriting factors, so they shape both your premium and your options. Insurers may not refuse to write or renew a homeowners policy solely because of roof age if the roof is less than 15 years old. For a roof 15 years or older, they must allow an inspection, and if it shows at least five years of remaining useful life, they may not refuse solely because of age.
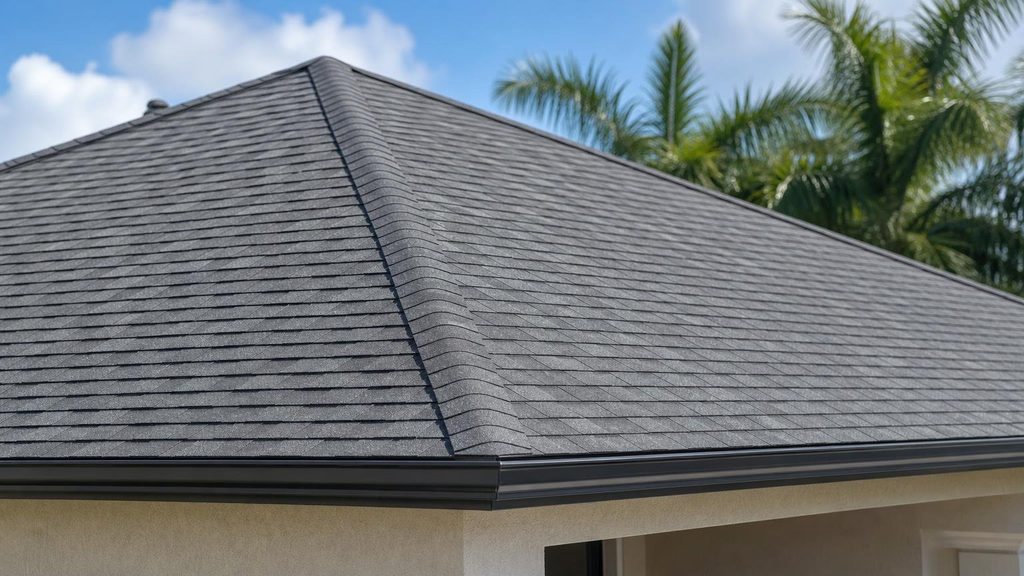
Florida insurers must also offer premium discounts for qualifying wind mitigation features, documented on the state’s Uniform Mitigation Verification Inspection Form. Features like roof-to-wall attachments, roof shape, and impact-rated windows or shutters can all earn credits. We’ll help you understand what a carrier needs and whether an updated inspection could lower your premium.
Dwelling coverage should be set at the cost to rebuild your home after a covered loss, not its market value or the assessed value on your Polk County Property Appraiser record. That assessed value is used for property taxes and often has little to do with what it would cost to rebuild today. A standard homeowners policy is built from several parts, and each one protects something different:
- Coverage A, Dwelling: the home itself, including the roof, walls, and built-in features.
- Coverage B, Other Structures: detached garages, sheds, and fences.
- Coverage C, Personal Property: your furniture, electronics, clothing, and belongings.
- Coverage D, Loss of Use: temporary housing and extra living costs if a covered loss forces you out of your home.
- Coverage E, Personal Liability: protection if someone is hurt on your property or you damage someone else’s property.
- Coverage F, Medical Payments: limited medical coverage for guests injured on your property, regardless of fault.
Water damage deserves a closer look, too. A plumbing leak, rain blowing in through storm damage, a drain or sewer backup, and rising floodwater can all look the same to a homeowner, but each may be treated differently under your policy. We’ll walk through how your policy handles each one before the next heavy rain tests it.
Sinkhole Coverage in Polk County
Every Florida property policy covers catastrophic ground cover collapse, the rare case where the ground suddenly gives way and the home becomes unsafe to live in. Broader sinkhole coverage, which can apply to less dramatic structural damage, is optional and may be available for an additional premium. Because Polk County has documented sinkhole activity, including in the Mulberry area, and decades of phosphate mining have reshaped the land around the city, it’s a decision worth making on purpose rather than by default.
The Flood Gap in a Homeowners Policy
Standard homeowners policies don’t pay for flood damage, even when the water comes from a hurricane or a slow-moving summer storm. Flood usually requires a separate policy, and more than 20% of flood insurance claims come from homes outside high-risk flood zones. If you’re insured through Citizens, flood coverage is also becoming a requirement for most policies with wind coverage.
Our Mulberry flood insurance guide explains how flood coverage works and how to protect your home and belongings.
Why an Independent Agency Matters in Florida’s Market
Florida’s homeowners market changes quickly, and carriers differ widely on roof rules, inspections, deductibles, and eligibility. As an independent agency owned and led by a licensed agent, we compare coverage from multiple carriers and explain your choices directly, so you can decide without pressure.
The type of insurer matters, too. Florida’s admitted insurers participate in the Florida Insurance Guaranty Association (FIGA), which may help pay certain covered claims if an insurer becomes insolvent, subject to FIGA’s limits and rules. Surplus lines insurers don’t participate in FIGA, but they can offer options for homes that are hard to place elsewhere. Citizens Property Insurance serves as the state’s insurer of last resort when eligible homeowners can’t find qualifying private coverage. We’ll explain not just the coverage and price, but what kind of company is behind the policy.
Policies, endorsements, and eligibility vary by carrier, so we review your current policy line by line. With a licensed local agent in your corner, you’ll get clear answers about your roof and deductible and coverage that protects your home, your family, and your savings.
Step-by-Step: How to Review Home Insurance in Mulberry
- Find your current declarations page and confirm the named insureds, property address, policy term, and dwelling limit.
- Compare your dwelling limit to the current cost to rebuild your home, rather than its market price or assessed value.
- Check both deductibles, your all other perils (AOP) deductible and your hurricane deductible, and translate any percentage into a dollar amount.
- Gather your roof information, including roof age, roof covering, repair records, and any recent inspection report.
- Locate your wind mitigation and 4-point inspection reports, if you have them. Many carriers ask for a 4-point inspection on older homes, and an updated wind mitigation inspection could earn additional credits.
- Review optional coverage, including broader sinkhole coverage and replacement cost coverage for your belongings.
- Decide whether a separate flood policy belongs in your protection plan.
- Ask Think Safe to compare your coverage across multiple carriers before your next renewal.
Frequently Asked Questions
Does homeowners insurance in Mulberry cover hurricane damage?
It depends what causes the damage. A Florida homeowners policy typically covers hurricane wind damage, subject to your hurricane deductible and policy terms. Flood damage is excluded from a standard homeowners policy and needs separate flood coverage.
How does a hurricane deductible work on a Florida home policy?
A hurricane deductible is separate from your regular deductible and is usually a percentage of your dwelling limit. A 2% deductible is the most common, and insurers must also offer $500, 5%, and 10% options. It applies once per calendar year, not per storm, for covered hurricane losses with the same insurer or insurer group.
Is sinkhole coverage worth adding in Polk County?
For many Polk County homeowners, it’s worth serious consideration. Catastrophic ground cover collapse is covered on every Florida property policy, while broader sinkhole coverage is optional and may cost additional premium and have different underwriting requirements. We can show you what the added coverage would cost on your home so you can decide.
Does my roof’s age affect my home insurance in Mulberry?
Yes. Roof age, roof covering, opening protection, and prior claims are major underwriting factors. Insurers may not refuse to write or renew solely because of age if the roof is under 15 years old. For older roofs, they must allow an inspection, and they may not refuse solely because of age if it shows at least five years of remaining useful life. A wind mitigation inspection can also document features that earn premium discounts.
Get a Mulberry Home Insurance Quote
Before your next renewal or the next storm, let a licensed local agent in your corner make sure your home is protected for what it would really take to rebuild.
Think Safe Insurance compares home insurance options built around your home’s rebuild cost, roof, deductibles, and protection needs, and we explain every choice clearly. Reviewing your whole household? We can also look at your Mulberry auto insurance at the same time. Call us at 863-356-4600, book a time to talk, or request a quote online.
When you think insurance… Think Safe!


 | Reviewed by Greg Martin Greg Martin has over 18 years of experience helping Florida families understand and protect their homes, vehicles, and other assets through homeowners, auto, flood, and specialty insurance. He is the owner of Think Safe Insurance, an independent Florida insurance agency. |
Last Reviewed: October 2026