
Seffner auto insurance works best when it’s built around how your household actually drives. A morning on I-4, a school run to Armwood, a quick trip down Kingsway Road: each one is routine until something goes wrong. Then the coverage you chose decides how much of the financial impact your policy handles.
Quick Takeaways
- Seffner Roads: I-4, I-75, US 92, and SR 574 all run through or beside Seffner, and Hillsborough County recorded 27,474 crashes in 2023.
- Seffner Households: Teen drivers headed to Armwood High School, adult children moving home, and I-4 commutes shape your policy, not the road you take.
- Everyday Seffner Coverage Moments: A rear-end collision at a light on SR 574 (bodily injury and property damage liability), an uninsured driver (UM/UIM, about one in five in Florida), and debris from I-4 (comprehensive).
- The Independent Advantage: We’re a Brandon agency right next door, and we compare multiple carriers and set limits around your household.
Auto Insurance for the Way Seffner Drivers Actually Drive
A normal day in Seffner can touch several roads. US 92 and Dr. Martin Luther King Jr. Boulevard (SR 574) run east and west through the community, Kingsway Road and Parsons Avenue connect neighborhoods, and I-4 and I-75 are close by for the drive toward Tampa, Brandon, or Plant City. From Kingsway and Lake Weeks to Toulon and Parsons Pointe, every Seffner household uses its vehicles a little differently.
Those roads don’t change what coverage you need. How you use your vehicles does. Someone who works from home and drives mostly around Seffner has a different mileage and use profile than someone commuting into Tampa five days a week, and your policy should reflect which one you are.
Households change, too. A teenager starts driving, an adult child moves home, or a commute turns into a work-from-home schedule. Each is a good reason to review your coverage instead of renewing the same policy every six months. For more about the community, see our guide to Seffner, FL.
How Florida Auto Insurance Protects Seffner Drivers
Florida builds auto insurance around a few core coverages. To register a vehicle, you carry Personal Injury Protection (PIP) and property damage liability (PDL). PIP helps pay part of your own medical expenses and lost income after an accident, regardless of fault. PDL pays for damage you cause to someone else’s vehicle or property.
Bodily injury liability is the coverage that pays for injuries you cause to other people after an at-fault crash. Florida doesn’t require it to register a vehicle, but drivers involved in certain injury crashes can be required to carry it under Florida’s financial responsibility law. We set bodily injury and property damage limits around your household’s situation, and there isn’t one right answer for everyone. We’ll walk you through the options and what each costs.
Liability and Uninsured Motorist Coverage in Seffner
Liability limits determine how much your policy pays if you injure someone or damage their property. A chain-reaction crash in heavy traffic near the I-4 and I-75 interchange can involve several vehicles and several injured people at once, which is exactly what liability limits are for. In 2023, Hillsborough County recorded 27,474 traffic crashes, 18,873 traffic injuries, and 230 traffic fatalities.
You can be a careful driver and still be hit by someone who isn’t insured. Uninsured and underinsured motorist coverage (UM/UIM) helps pay covered medical expenses and lost wages for you and your passengers when another driver causes an accident but has no insurance, or not enough bodily injury coverage. The driver who rear-ends you at a light on SR 574 could easily be one of them: Florida’s estimated uninsured motorist rate was 20.6% in 2023, seventh-highest in the nation, or about one in five drivers.
UM/UIM isn’t required, but it’s recommended considering how many people on the road have low or no coverage. It’s available as stacked or non-stacked. We’ll explain the difference before you decide.
Comprehensive and Collision Coverage for Seffner Drivers
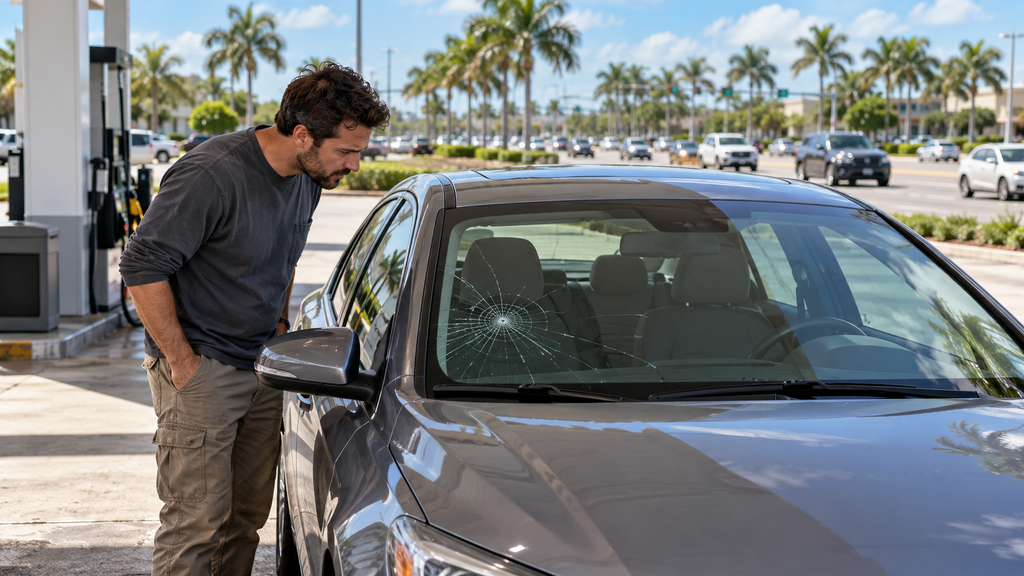
Liability protects others when you’re at fault. Comprehensive and collision protect your own vehicle. Collision covers damage from an impact with another vehicle or object, whether that’s a bumper tap in rush hour on US 92 or a slide into a guardrail. Comprehensive covers non-collision losses: theft, fire, vandalism, storm damage, and the rock kicked up by a truck on I-4 that cracks your windshield.
Flood damage to your car is also handled under comprehensive, subject to your deductible, not under flood insurance. Your Seffner flood insurance is a separate decision focused on your home and belongings.
If you finance or lease, your lender or lessor will require comprehensive and collision. If you own an older vehicle outright, the decision is yours, and we’ll help you weigh the vehicle’s value, the deductible, and the premium. We also review the real rating inputs behind your quote: garaging address, annual mileage, vehicle use (commuting, pleasure, or business), listed drivers, and the vehicles you own.
Adding a Teen Driver to Your Seffner Auto Policy
Getting that first license is exciting, and it’s also one of the biggest changes a household policy goes through. Whether your teenager is driving to Armwood High School on US 92, to a part-time job, or to activities around Brandon and Seffner, review the policy before regular driving begins.
Adding a young driver changes your premium and your liability picture. We’ll review who needs to be listed, which vehicles they’ll drive, which driver discounts are available, and whether your liability and UM limits still fit. Discounts and eligibility vary by carrier, which is why comparing multiple carriers matters.
The same goes when an adult child moves home or another household member starts regularly driving one of your vehicles. Accurate driver information is what keeps a claim simple.
Auto and Home Insurance Together
If you own your Seffner home, it helps to look at auto and home insurance together. While many carrier in FL don’t offer home and auto together, some carriers have a discount when you have both policies with the same agency. That’s where comparing multiple carriers pays off. Our Seffner home insurance page covers the property side.
Step-by-Step: How to Review Auto Insurance in Seffner
Review your policy whenever something changes: a new driver, a new vehicle, a new commute, or a new home. Here’s how.
- Gather your current declarations page, vehicle information, and any lender or lease requirements.
- Check your bodily injury and property damage liability limits and make sure they fit your household’s situation.
- Review UM/UIM, including whether stacked or non-stacked is right for your household.
- Review comprehensive and collision deductibles against each vehicle’s value and any financing requirement.
- Confirm every household driver, including any new teen driver, plus each vehicle, garaging address, mileage estimate, and vehicle use is listed accurately.
- Call Think Safe to compare multiple carriers side by side and walk through the tradeoffs with a licensed local agent.
Frequently Asked Questions
What auto insurance does Florida require, and what else should Seffner drivers carry?
To register a vehicle, Florida requires PIP and property damage liability. Those cover part of your own medical costs and damage you cause to someone else’s property. Bodily injury liability covers injuries you cause to others after an at-fault crash, and UM/UIM protects you when the other driver can’t pay. We’ll build these around your household.
Does commuting from Seffner to Tampa on I-4 change my coverage or my rate?
It can change your rate, not your coverage. Annual mileage, vehicle use, and garaging address are rating factors, and each carrier weighs them differently. The right limits depend on your household, not which roads you drive, so just make sure your vehicle use is listed accurately.
What does uninsured motorist coverage do if an uninsured driver hits me?
UM pays covered medical expenses and lost wages for you and your passengers when the at-fault driver has no insurance. UIM does the same when the other driver’s bodily injury limits are too low. With about one in five Florida drivers uninsured, it’s one of the most valuable coverages you can carry.
Does uninsured motorist coverage repair my car?
No. UM/UIM covers injury-related losses, not vehicle repairs. Collision coverage pays for covered damage to your car after a crash, subject to your deductible. We review both because they do different jobs.
Is a cracked windshield or flood damage to my car covered?
Yes, under comprehensive coverage, subject to your deductible. That includes windshield damage from road debris, falling trees, hail, storm damage, and flood damage to a vehicle. If your policy is liability-only, none of that is covered, so confirm comprehensive is on every vehicle you’d want repaired or replaced.
In Florida, the front windshield is covered with $0 deductible if you have comprehensive coverage. This will still show in your claims history, so it can impact future rates. Also, some carriers have limitations on how much they will pay, so it’s always good to report it to the claims department and see who their recommended vendors are.
Do I need to tell my insurance company when my teenager starts driving?
Yes. Call us when a household member gets licensed or starts regularly driving, so they’re listed and rated correctly. Doing it before an accident keeps a claim from turning into a coverage question.
Get a Seffner Auto Insurance Quote
Your policy should fit the way your household actually lives and drives. Let’s review your limits, UM/UIM, deductibles, and vehicle coverage so you can make confident choices for your family. Call 813-425-1626, request a quote online, or schedule an appointment.
When you think insurance… Think Safe!


 | Reviewed by Greg Martin Greg Martin has over 18 years of experience helping Florida families understand and protect their homes, vehicles, and other assets through homeowners, auto, flood, and specialty insurance. He is the owner of Think Safe Insurance, an independent Florida insurance agency. |
Last Reviewed: October 2026