
Seffner home insurance starts with the home you actually own. An established ranch in Greenewood, a 1970s home near Lake Weeks, and a mid-2000s home in Chestnut Forest each raise different questions about roofs, rebuild cost, and wind features, and your policy should answer the ones that apply to yours.
Quick Takeaways
- Seffner Homes: Greenewood’s ranch-style homes, the 1970s lake-access streets near Lake Weeks, and newer communities like Chestnut Forest and Estates at Parsons Pointe each raise different roof and rebuild-cost questions.
- Seffner Roofs and Storms: Roof age, wind-mitigation credits, and the separate hurricane deductible, most commonly 2% of your dwelling limit, shape your policy and your premium.
- Seffner Water and Ground: Lake Weeks and Lake Hooker lie just east of Seffner, flood is excluded from a homeowners policy, and Faithway Drive’s 2013 sinkhole made sinkhole coverage a local question.
- The Independent Advantage: We’re a Brandon agency right next door, and we compare multiple carriers for the home you own.
Home Insurance for Seffner’s Neighborhoods
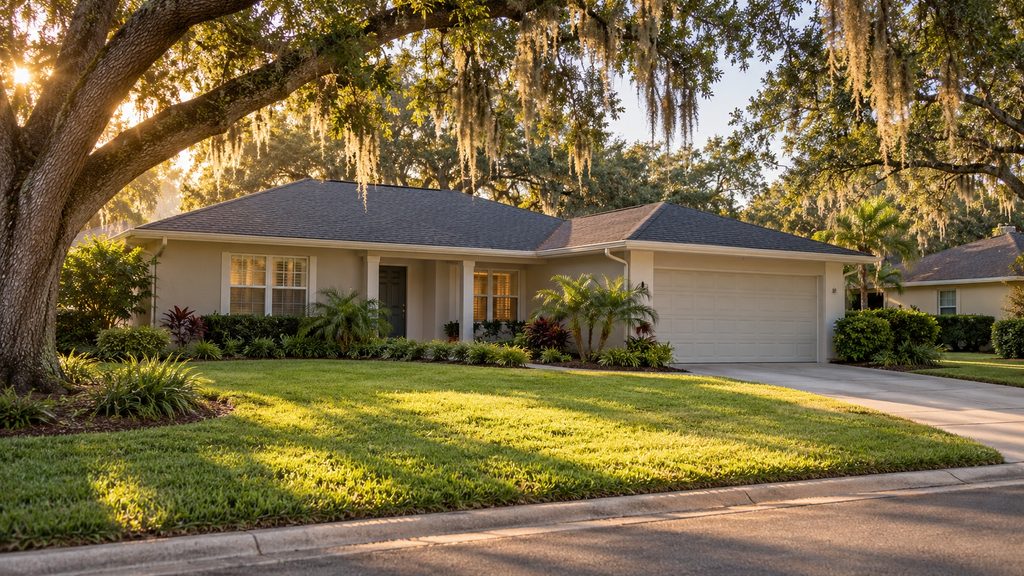
Seffner’s housing spans several eras. Greenewood has established ranch-style homes on roughly quarter-acre lots, the Lake Weeks subdivision dates to the 1970s, and Chestnut Forest and Estates at Parsons Pointe were built in the mid-2000s. A roof replacement, an enclosed patio, or a remodeled kitchen changes what an insurer needs to know about a home, and a newer home has its own questions about floor plan, finishes, and construction details.
Two homes on the same Seffner street may have very different insurance needs. We look at your roof, your construction, and your updates, then build coverage around them. For more about the community, see our guide to Seffner, FL.
Could Your Seffner Home Be Rebuilt for Its Current Limit?
Your dwelling limit is not your home’s market value, tax assessment, or mortgage balance. It should reflect the cost to rebuild the structure with today’s labor and materials after a covered loss. Land value and local real estate demand move your sale price, but they don’t change what it costs to rebuild.
For an established Seffner home, we ask what has changed since the policy was written: an enclosed porch, added living space, new cabinets, remodeled bathrooms. For a newer home, we review square footage, finishes, and construction details. A homeowners policy also covers other structures, your belongings, additional living expenses while you’re out of the home, and personal liability, so we review those limits too.
Roofs and Wind Mitigation on Seffner Homes
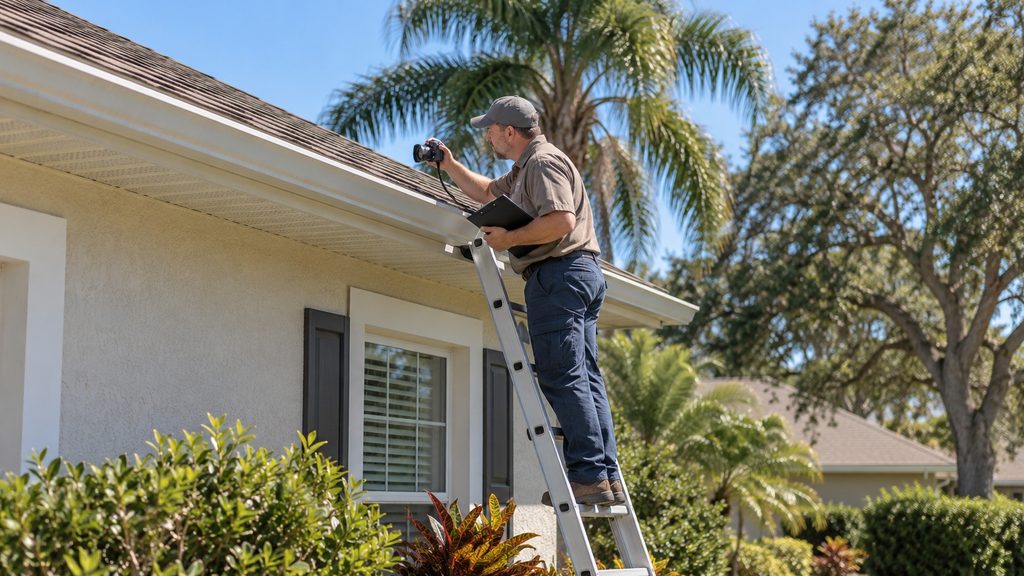
Strong wind and falling branches damage homes well inland, and in an older Seffner neighborhood with mature oaks, the roof is often the first thing we review. Roof age, roof covering, opening protection, and prior claims are major underwriting factors in Florida. Florida insurers can’t refuse to write or renew a policy solely because of roof age if the roof is under 15 years old. For a roof 15 years or older, the insurer must allow an inspection, and it can’t refuse solely because of age if the inspection shows at least five years of remaining useful life.
Florida insurers must also offer premium discounts for qualifying wind-mitigation features, such as certain roof-to-wall connections and opening protection, documented on the state’s Uniform Mitigation Verification Inspection Form. If you’ve replaced your roof, your carrier needs that information to apply the credits it earns. We can review an existing inspection, help you know what to ask an inspector, and compare how carriers recognize the features on your home.
Your Hurricane Deductible in Real Dollars
Florida home policies carry a separate hurricane deductible, usually a percentage of your dwelling limit. A 2% deductible is the most common, and insurers must also offer $500, 5%, and 10% options. For example, a 2% hurricane deductible on a $400,000 dwelling limit is $8,000. It applies on a calendar-year basis for covered hurricane losses with the same insurer or insurer group, so it doesn’t start over with each storm.
When we compare Seffner home insurance options, we look at the premium and at what each deductible means in actual dollars, so you know the tradeoff before a claim.
Sinkhole Coverage in Seffner
Seffner became nationally known when a sinkhole opened beneath a home on Faithway Drive in 2013, and the same spot later reopened, drawing national news coverage. The dramatic collapses you see on the news are usually catastrophic ground cover collapse, which most standard homeowners policies in Florida cover. Broader sinkhole coverage is available, but it often comes with strict underwriting and a 10% deductible.
Flood and Water Damage Near Seffner’s Lakes
Seffner is inland, but it sits among lakes and creeks. Lake Weeks, a 53-acre lake, and Lake Hooker lie just east of the community, in the Pemberton Creek and Baker Canal watershed. Whether a particular home is in a flood zone depends on the property, not the community name.
Water that comes from inside the home, like a burst pipe, is a homeowners claim under the water damage coverage. Water that rises from outside is flood, and standard homeowners policies exclude it, so it takes a separate flood policy to protect your home and belongings. Our Seffner flood insurance page explains how that coverage works.
Home and Auto Insurance Together
If you’d like your home and vehicles reviewed together, we can also look at Seffner auto insurance. Two carriers can look at the same Seffner home and offer very different roof rules, deductible options, and endorsements, and sometimes one carrier fits your home while another fits your auto. As an independent agency, we compare them side by side.
Step-by-Step: How to Review Home Insurance in Seffner
- Confirm the dwelling limit. Compare your current limit with the cost to rebuild, including updates, square footage, and construction details.
- Review the roof and wind mitigation. Gather the roof’s age and replacement information, then check whether you have a current wind-mitigation inspection and the credits that go with it.
- Know every deductible. Look at your standard deductible and the separate hurricane deductible, including the dollar amount each percentage represents.
- Check sinkhole and water coverage. Confirm what your policy says about catastrophic ground cover collapse and broader sinkhole coverage, and how it treats water that comes from inside the home.
- Address the flood exclusion. Consider separate flood insurance for the structure and your belongings, even if your lender doesn’t require it.
- Call Think Safe. We’ll compare multiple carriers side by side and walk through the tradeoffs with a licensed local agent.
Frequently Asked Questions
Does an older Seffner home cost more to insure?
Not by age alone. Insurers look at the roof’s age and covering, construction, updates, and claims history. An older home with a newer roof and documented wind-mitigation features can look very different to a carrier than one with an aging roof and incomplete information.
Does my Seffner homeowners policy cover sinkhole damage?
Most standard Florida homeowners policies cover catastrophic ground cover collapse, which is what typically makes the news. Broader sinkhole coverage is available, but it often comes with strict underwriting and a 10% deductible.
How does a hurricane deductible work on a Florida home policy?
A hurricane deductible is separate from your standard deductible and is usually a percentage of the dwelling limit. A 2% deductible is the most common, and insurers must also offer $500, 5%, and 10% options. It applies on a calendar-year basis for covered hurricane losses with the same insurer or insurer group.
Does home insurance cover flooding?
No. Standard homeowners policies exclude flood damage. It usuallytakes a separate flood policy to protect your home and belongings from rising water, whether or not you’re in a high-risk flood zone.
How can a wind mitigation inspection or a newer roof lower my premium?
Florida insurers must offer premium discounts for qualifying wind-mitigation features documented on the Uniform Mitigation Verification Inspection Form. A newer roof, along with features such as roof-to-wall connections and opening protection, also affects carrier eligibility and pricing. We’ll review what your home qualifies for.
Should I update my insurance after remodeling my home?
Yes. An addition, an enclosed patio, or a kitchen remodel changes your home’s rebuild cost. Tell us what changed so we can review your dwelling limit.
Get a Seffner Home Insurance Quote
Whether you’re buying in Seffner, updating an established home, or preparing for your next renewal, let’s review your rebuild limit, roof information, hurricane deductible, and sinkhole and flood options. Call 813-425-1626, request a quote online, or schedule an appointment, and we’ll compare options for you.
When you think insurance… Think Safe!


 | Reviewed by Greg Martin Greg Martin has over 18 years of experience helping Florida families understand and protect their homes, vehicles, and other assets through homeowners, auto, flood, and specialty insurance. He is the owner of Think Safe Insurance, an independent Florida insurance agency. |
Last Reviewed: October 2026